
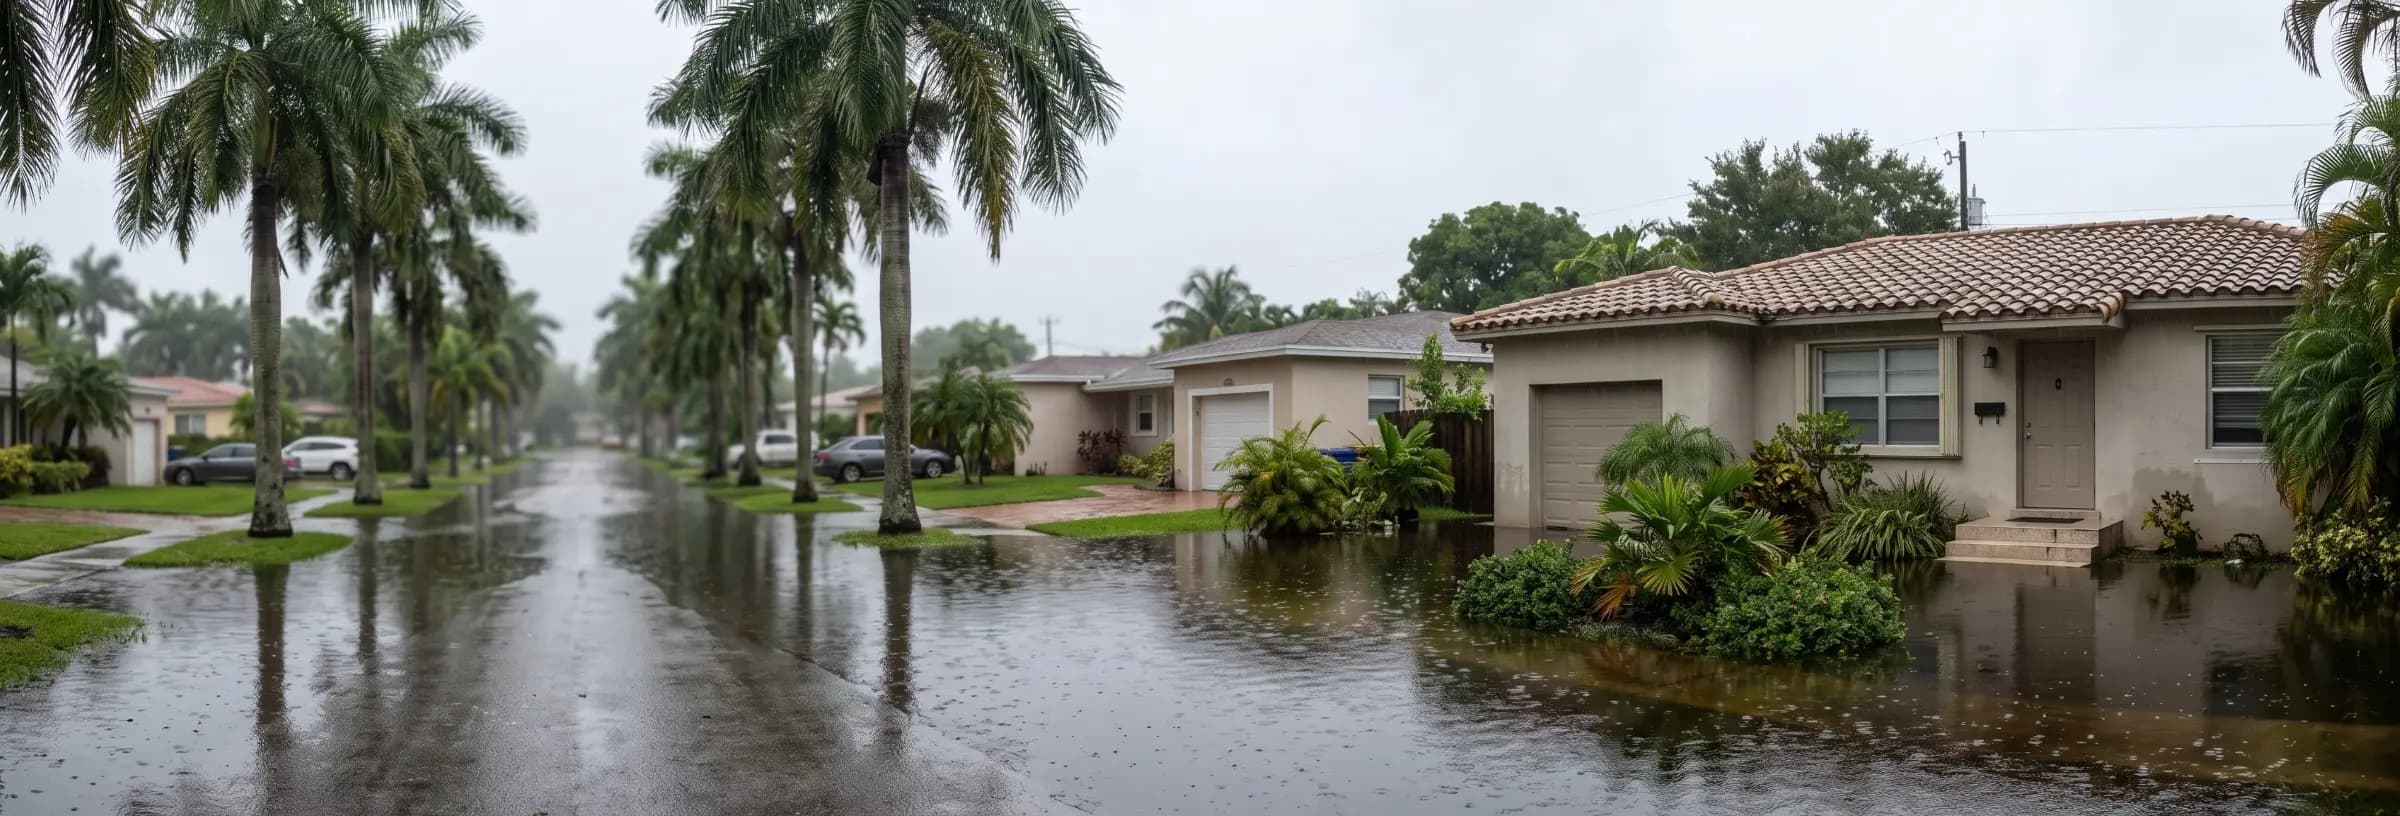
Water inside a Miami home has a short window before a drying job turns into a rebuild, because warm, humid air slows drying and speeds mold growth. Hurricanes, tidal flooding, Florida's claim deadlines, and local permit rules change what the job costs and how fast you need to move.
In Miami, water damage restoration is the professional process of extracting water, drying structural materials, cleaning, and repairing a home, performed to the ANSI/IICRC S500 standard for professional water damage restoration. Florida does not license water extraction and drying as a separate trade, so IICRC credentials and a written scope are the main ways to screen a company, while the rebuild falls under Florida contractor licensing.
Key insights
- Typical cost. Water damage restoration in Miami costs $1,500–$7,000 for one affected area, while Category 3 flood or tidal water on the ground floor can reach $10,000–$35,000 or more.
- Outside water is always Category 3. Under ANSI/IICRC S500, flood, storm surge, and tidal water that enters a home requires removal of porous materials such as carpet padding and lower drywall, which is why those jobs cost far more than plumbing leaks.
- Florida deadlines are short. Florida Statute 627.70132 bars a claim unless the insurer receives notice within 1 year of the loss, or within 18 months for a supplemental claim, and the insurer must pay or deny within 60 days of notice.
- Hurricane deductibles are separate. A Florida hurricane deductible is typically 2, 5, or 10 percent of the dwelling limit and applies to wind damage, while plumbing leaks and AC overflows fall under the standard deductible and flood needs its own policy.
- Assignment of benefits is banned. On policies issued on or after January 1, 2023, a restoration company cannot take over your claim benefits under Florida Statute 627.7152. The bill stays your responsibility.
- The 50 percent rule. In a flood zone, repairs that cost 50 percent or more of the structure's pre-damage market value trigger current floodplain requirements, which can include elevating the home before a repair permit is issued.
First 48 hours of water damage in Miami
In the first 48 hours, find and stop the water source, make the area electrically safe, photograph the damage, notify your insurer in writing, and start drying with an IICRC credentialed company. The EPA says mold can start growing on wet materials within 24–48 hours, and Miami's warm indoor temperatures and humid outdoor air make that window harder to beat.
 Photograph the water line and damaged belongings before moving or drying anything, then email the photos to your insurer so the dated record backs up your written notice.
If the loss happened during a named storm, expect more than one claim, because wind driven rain and flood water are handled under different policies and deductibles. Mitigation can start right away either way, and Florida policies expect you to protect the property from further damage. Reasonable drying costs belong in the claim, and the receipts are the proof.
1. Identify the water source
Rain, street, or tidal water entering from outside is flood water, a failed pipe or appliance is plumbing water, and rain coming through a roof or window opening is storm water. Florida homeowners and flood policies respond to different sources. Note which one you have before you describe the loss.
2. Make the area electrically safe
Switch off power at the breaker only if the panel is dry and you can reach it without stepping through water, and call an electrician or Florida Power & Light if not. If water is still moving, sewage is involved, or the panel is wet, treat it as an emergency water damage restoration situation and stay out of the room until power is confirmed off. Run generators outdoors, far from doors and windows, because carbon monoxide poisoning is a recurring danger during post-hurricane power outages.
3. Photograph everything and put the timeline in writing
Photograph the source, the water line on walls, and damaged belongings before moving anything, then send your insurer a short written notice. Florida's 7 day acknowledgment clock starts when the insurer receives your communication. An email after your phone call gives you a dated record.
4. Start drying the same day
Remove standing water and start airflow right away, and call a restoration company with IICRC credentials while you wait for the insurer, since drying cannot wait for adjuster scheduling. Keep doors and windows closed and run air conditioning or dehumidifiers, because Miami's outdoor air is often wetter than the air inside a drying home.
5. Check the flood zone before you repair
If the loss was flood damage, look up the address with the Miami-Dade Flood Zone Hotline at 305-372-6466 and ask your city's building department about substantial damage before you order repairs. The answer tells you whether you may be required to elevate the home before a repair permit is issued.
Water damage categories and classes
ANSI/IICRC S500 sorts water damage into three categories by contamination level and four classes by how much water the materials absorbed and how fast it will evaporate. The category decides what gets cleaned or thrown away, and the class decides how much drying equipment the job needs.
A category can get worse with time. Clean water from a supply line that sits for 48–72 hours can degrade to Category 2, and Miami's warm indoor temperatures speed that up, while water that enters from outside is Category 3 from the moment it enters the home.
| Category | What it means | Common Miami sources |
|---|---|---|
| Category 1 | Water from a sanitary source with no significant contamination | Supply line failures, water heater leaks, and sink or tub overflows |
| Category 2 | Significant contamination that can cause illness if exposed or consumed | Washing machine or dishwasher discharge, AC condensate that has stood in a pan or insulation, and Category 1 water that has aged |
| Category 3 | Grossly contaminated water that can cause severe illness | Storm surge, king tide and street flood water, sewage backups, and standing water that has grown microbes |
Treat a sewage backup or any water of unknown origin as Category 3 until a technician classifies it. Porous materials that touch Category 3 water, including carpet, padding, and drywall, are removed instead of dried.
Class 2 covers most appliance and supply line leaks, where a whole room of carpet and padding is wet, and Class 3 describes water that came from above, as in an air handler overflow or a roof leak. Class 4 covers water bound in dense materials such as concrete block, plaster, and hardwood, which dry slowly and need specialty equipment.
Water damage restoration cost in Miami
Water damage restoration in Miami typically costs $1,500–$7,000 for one affected area, based on RestoreAdvisor estimates as of October 2026. Costs rise with Category 3 water, multiple rooms, high rise access, and slow response, and they fall when drying starts within the first day.
 Drying equipment is billed by the day, so the estimate should list how many units run and for how many days. A job that starts late runs longer and costs more.
No public dataset publishes Miami only invoices, so these figures start from national ranges and adjust for conditions that shape local losses: ground floor flood exposure, a year round cooling season, slab foundations, condo access, and post-storm demand. Mitigation (extraction and drying) and reconstruction (drywall, flooring, paint) are usually billed as separate scopes, and an insurance estimate often splits them the same way.
| Scenario | Cost | What drives it |
|---|---|---|
| Water heater or appliance leak caught within a day | $500–$2,500 | Clean water and a small footprint; units in closets or garages add cabinet or drywall repair |
| AC condensate overflow from an air handler closet or ceiling | $800–$4,000 | Wet insulation and drywall below the unit, often found after weeks of slow leaking |
| Burst or leaking supply line in one room | $1,500–$7,000 | Extraction, drying equipment for 3–5 days, and flooring or drywall replacement |
| Slab leak with wet flooring | $1,500–$6,000 | Cleanup only; locating and repairing the line under the slab is billed separately |
| Roof leak after a storm | $1,000–$6,000 | Wet insulation and ceilings; the roof repair is a separate roofing invoice |
| Sewage backup (Category 3) | $2,000–$10,000 | Disinfection, protective equipment, and removal of porous materials |
| Leak from a condo unit above that reaches two floors | $3,000–$15,000+ | Building access, shared walls and risers, and work in more than one unit |
| Flood or tidal water on the ground floor (Category 3) | $10,000–$35,000+ | Flood cuts, flooring, drywall, and contents; severe multi level losses can pass $75,000 |
National water damage restoration cost ranges set the baseline, and Miami jobs move above or below them with the contamination category, the hours before drying starts, storm demand, and high rise access. Each of those shows up as a line on a written estimate, and you can ask the company to point to it.
Contamination category
Category 1 jobs are mostly extraction and drying, while Category 3 flood, tidal, and sewage jobs add protective equipment, disinfection, and removal of porous materials under ANSI/IICRC S500. That added tear out is where most of the price gap comes from.
Hours before drying starts
Drying that starts within the first day keeps more drywall and carpet padding salvageable. Every extra day they stay wet adds demolition and replacement cost. Equipment is billed by the day, so a job that starts late also runs longer.
Storm demand
After a named storm, crews, dehumidifiers, and drywall suppliers tighten across Miami-Dade and Broward at once. The same job starts later and costs more than it would in a quiet week. Insurers' price lists also shift after regional events, which can move an adjuster's estimate away from a contractor's bid.
High rise and condo access
Elevator reservations, floor protection, and building management approval add time to work in a tower, and a leak that crosses a shared wall adds a second unit to the scope. Expect a condo job to run longer than a comparable single family scope.
DIY or pro water cleanup in Miami
A homeowner can handle a small spill of clean water that is caught within hours and stays on a hard surface, but most Miami losses cross the line quickly. Humid air slows drying and concrete block walls hold water. The real question is whether the water reached anything that cannot be dried by the surface.
 Moisture readings logged room by room give an insurer the documentation behind a drying scope, and they can show wet material behind a surface that looks dry.
The safest rule is to call a professional whenever water has moved into a wall, under flooring, or into insulation, or whenever it came from outside the home or from a sewage backup. Cleanup that looks finished can leave a damp wall cavity behind, and a company that logs moisture readings gives you the documentation an insurer asks for later.
| Situation | DIY or pro | Why |
|---|---|---|
| Clean water on tile or sealed concrete, dried within a day | DIY | Surface water dries with towels, fans, and a dehumidifier before it reaches porous material |
| AC drain pan overflow caught the same day | DIY | Clear the drain line and dry the area, then call a pro if insulation or the ceiling below is wet |
| Water in a wall, under flooring, or in insulation | Pro | Wall cavities and subfloors stay damp while the surface looks dry, and mold can start within 24–48 hours |
| Storm surge, canal, or street flood water | Pro | Category 3 water carries contamination that needs protective gear and removal of porous materials |
| Sewage backup | Pro | Category 3 from the start, with health risks from direct contact |
| Water near outlets, panels, or ceiling lights | Pro | Shut off power at the breaker first and have an electrician clear the circuit before anyone enters |
Why water damage differs in Miami
Miami homes take water damage differently because the city is flat, sits only a few feet above sea level on porous limestone, and has humid air in every month of the year. Water arrives from above as heavy rain, from below as rising groundwater, and from the side as storm surge or tidal flooding.
NOAA climate records show more than 60 inches of rain a year at Miami International Airport, concentrated from mid-May through early October, and average relative humidity above 65 percent in every month. That leaves wet materials with little help from the outdoor air. Open windows add moisture instead of drying a wet room.
Groundwater sits close to the surface
USGS records from Hurricane Donna in 1960 and Tropical Storm Dennis in 1981 show groundwater levels rising 4–8 feet across much of south Miami-Dade, with flooding over roughly 600 square miles. Because Miami sits on porous limestone, water also rises through the ground, which is why slabs and wall bottoms get wet with no visible source.
Concrete block walls hold water
Concrete block walls absorb and release water slowly, which keeps a wall damp after the surface looks dry, and the layers under flooring can stay damp the same way. A moisture meter reading compared with an unaffected area of the same material, as ANSI/IICRC S500 describes, is the reliable test.
Miami flood and hurricane history
Miami's major water events include Hurricane Andrew in 1992, Hurricane Irma in 2017, and the heavy rain and tidal flooding of November 2023 and June 2024. Andrew and Irma shaped Florida's building codes and insurance rules, while the recent floods show that water now reaches neighborhoods far from any storm track.
 Water welling up through a storm drain on a clear day is tidal flooding, which counts as flood water, not storm or plumbing water. A flood policy responds to it, not a standard homeowners policy.
The National Weather Service reports that Andrew's 1992 landfall in south Miami-Dade destroyed or damaged well over 100,000 homes. Hurricane Irma in September 2017 produced more insurance claims in Miami-Dade than in any other Florida county, about 152,200 according to the Florida Office of Insurance Regulation, and about 30 percent of them closed without payment.
NOAA's Virginia Key tide gauge recorded nine high tide flood days in 2019 compared with none in 2000, and the fall king tides put water in streets on sunny days. Heavy rain in November 2023 left streets in Miami, Miami Beach, and Miami Springs impassable, and three days of rain in June 2024 caused water damage from flooding in homes across South Florida.
Miami-Dade County lists its effective FEMA flood maps as dating to September 11, 2009, and revised maps reported in June 2024 would put about 252,015 structures in the special flood hazard area, 45,420 more than before. The Miami-Dade Flood Zone Hotline at 305-372-6466 can confirm which map applies to an address, because insurers and permit offices use the map in effect.
Common water sources in Miami homes
Water enters a Miami home through four common routes: storm driven rain, air conditioner condensate, slab and plumbing leaks, and failed roofs, windows, or doors. The route determines how the water travels, how long it goes unseen, and which part of a policy responds.
 A ceiling stain near a vent or air handler points to condensate, while one under a roof penetration points to a roof leak. Photograph it with a date before any repair and note when you first saw it.
Hurricane and storm damage
A Miami hurricane claim usually splits in two: wind driven rain through a damaged roof, window, or door falls under the homeowners policy and its hurricane deductible, while storm surge or rising canal water is paid only by a flood policy. That split means storm and hurricane water damage is usually claimed under two policies, with two adjusters and two deductibles.
A roof opened by wind or a fallen limb lets water into insulation and ceilings before a stain appears. Tarp the opening, photograph the damage, and keep receipts, because a roof that looks sealed can still hold wet insulation.
AC condensation damage
Miami air conditioners run most of the year, so a clogged condensate line, a cracked drain pan, or a stuck float switch is one of the most frequent non-storm sources of water in the home. The overflow reaches the air handler closet, attic, or ceiling, and HVAC water damage from condensation can soak insulation and drywall for weeks before a stain appears.
Air handlers in attics, garages, and utility closets are the usual sources, and the water often travels along framing before it shows. Because these leaks build slowly, adjusters ask how long the leak ran, and damage from constant or repeated leakage can be excluded. Keep dated records of AC service visits, the first stain you noticed, and the day you shut the system off, because that timeline supports a sudden and accidental claim.
Slab leaks and plumbing
Many Miami homes sit on concrete slabs with no crawl space or basement, so a slab leak, a supply or drain line that fails inside or beneath the slab, can run for weeks before anyone sees it. The first sign is often a warm spot on the floor, a rising water bill, or the sound of running water with every fixture off.
Water from a slab leak travels sideways under flooring before it shows. Wet carpet or lifted floor planks may mean the leak has run for weeks. A plumber has to locate and isolate the line first, and restoration begins once the water is shut off and the repair path is clear.
Homes with older drain lines, including cast iron in mid-century construction, can leak from the inside out as the pipe corrodes. Policies can treat the access work needed to reach the pipe differently from the water damage itself, so ask your agent how yours handles slab leaks before you file.
Roof, window, and door leaks
Wind driven rain is a leading cause of storm related water damage in Miami, and it enters through the roof, windows, and doors before the structure itself fails. In Miami, water damage from a roof leak usually starts at flashing, valleys, ridge caps, or tile underlayment and soaks attic insulation before it reaches a ceiling.
Tile roofs hide damage well. Tiles can look intact while the underlayment beneath them has failed. A ceiling stain after a storm is a reason to inspect the roof even when nothing is visibly missing.
Windows and doors leak when seals, flashing, or thresholds fail under pressure from wind driven rain. A window or door leak often shows as staining below the frame or bubbling paint at the wall base, and older jalousie windows and sliding glass doors are common entry points.
Signs of water damage in a Miami home
The common signs of water damage in a Miami home are a musty smell, a brown ceiling stain, bubbling paint, a warm spot on a slab floor, and a water bill that rises with no change in use. Slab construction and constant air conditioning hide leaks inside walls and under floors. Check early signs promptly instead of waiting to see if they spread.
 With every fixture off, a dial that still moves means water is running somewhere in the system. Photograph the reading with a date, since insurers ask how long a leak ran.
The sign and its location usually point to the source. Stains under an air handler suggest condensate, stains under a roof penetration suggest a roof leak, and a warm floor spot or a bill that climbs with no change in use points to a slab leak.
| Sign | Likely cause | Where to look |
|---|---|---|
| Musty or sour smell | Damp insulation or drywall behind a wall | Closets, garages, and rooms near the air handler |
| Brown stain spreading on a ceiling | Roof leak, AC pan overflow, or an upstairs line | Below the air handler, bathrooms, and roof penetrations |
| Bubbling or peeling paint | Moisture moving through the wall from inside | Lower walls, exterior corners, and bathroom walls |
| Warm or damp spot on a slab floor | Slab leak on a hot or cold supply line | Hallways and floors under tile |
| Water bill rises with no change in use | Hidden leak in a supply line or irrigation | Water meter, with every fixture off, to see if the dial moves |
| Cracked or loose tile | Moisture under the tile or slab movement | Bathrooms, kitchens, and entry doors |
Florida insurance rules for water damage
Florida homeowners policies generally cover sudden and accidental water damage, such as a burst pipe or appliance failure, but exclude flood water and damage from constant or repeated leakage. Whether homeowners insurance covers water damage turns on where the water came from and how long it ran, so document both. Citizens Property Insurance, the state backed insurer, limits nonweather water losses such as a broken pipe or a leaking water heater to $10,000 unless the policyholder uses its managed repair program, and many private insurers that took over Citizens policies carry a similar cap. Check your declarations page for a water damage limit before a loss, because a $10,000 cap can fall short of a multi room job.
Florida sets short deadlines on both sides of a claim. Under Florida Statute 627.70132, a claim or reopened claim is barred unless the insurer receives notice within 1 year of the loss, and a supplemental claim must be noticed within 18 months. Statute 627.70131 requires the insurer to acknowledge your communication within 7 days, inspect within 30 days of receiving proof-of-loss statements, and pay or deny within 60 days of notice.
| Claim step | Deadline | Statute |
|---|---|---|
| Report a new or reopened claim | Within 1 year of the date of loss | 627.70132 |
| Report a supplemental claim | Within 18 months of the date of loss | 627.70132 |
| Insurer acknowledges your communication | Within 7 calendar days | 627.70131 |
| Insurer inspects after proof of loss | Within 30 days of receiving it | 627.70131 |
| Insurer pays or denies the claim | Within 60 days of notice | 627.70131 |
Payments made after the 60 day window bear interest, and disputed claims can go to free mediation through the Florida Department of Financial Services, Division of Consumer Services, under the Homeowner Claims Bill of Rights. Hidden damage found after repairs begin can be added as a supplemental claim, which is why the 18 month window in Florida Statute 627.70132 matters. Condo owners with loss assessment coverage have a longer outer limit, because a notice of a loss assessment claim may not come later than 3 years after the date of loss.
Hurricane deductible and flood coverage
A Florida hurricane deductible is a separate deductible, typically 2, 5, or 10 percent of the dwelling coverage limit, that applies to windstorm damage during a hurricane and not to plumbing leaks, AC overflows, or flood. Insurers must offer options of $500, 2 percent, 5 percent, or 10 percent, according to the Florida Department of Financial Services.
 Rain that enters through a window or roof opening damaged by wind is a homeowners claim, and the hurricane deductible applies when the loss falls inside the deductible period. Water that rises from outside is a flood policy claim instead.
On a home insured for $400,000, a 2 percent hurricane deductible is $8,000, a 5 percent deductible is $20,000, and a 10 percent deductible is $40,000. The deductible period begins when the National Hurricane Center issues a hurricane warning for any part of Florida and runs until 72 hours after the last hurricane watch or warning ends, and it applies once per calendar year.
| Water source | Homeowners policy | Flood policy |
|---|---|---|
| Burst pipe or appliance leak | Covered if sudden; standard deductible | Not covered |
| AC condensate overflow | Covered if sudden; excluded if gradual | Not covered |
| Rain through a roof or window damaged by wind | Covered; hurricane deductible applies in a hurricane | Not covered |
| Storm surge, tidal, or street flooding | Not covered | Covered up to policy limits |
| Sewer or drain backup | Only with a water backup endorsement | Only when part of a general flood |
| Slow or long term leak | Usually excluded as constant seepage | Not covered |
NFIP and private flood insurance cover rising water that homeowners policies exclude, but NFIP policies carry a 30 day waiting period. A policy bought after a storm forms does not cover that storm. NFIP building coverage tops out at $250,000 and contents at $100,000.
Who pays for restoration in Florida
A Miami homeowner owes the restoration bill, and the insurer reimburses covered amounts under the policy, because Florida bans assignment of benefits on policies issued on or after January 1, 2023. Under Florida Statute 627.7152, an attempt to assign post-loss benefits under those policies is void. A contractor cannot step into your claim.
A direction to pay lets an insurer send money to the contractor, but it generally does not transfer your claim or relieve you if the insurer denies or underpays. Read any work authorization before you sign it, and keep the paperwork you would need for filing a water damage insurance claim, including the estimate, the drying log, and receipts.
Replacement cost or actual cash value
Replacement cost coverage pays to repair at current prices, while actual cash value subtracts depreciation and pays less up front. Ask your insurer whether withheld depreciation is paid after the work is finished and what proof it needs.
Who receives the check
Some insurers pay a contractor directly, and others issue the check to you, with your mortgage lender named on structural damage payments. A lender endorsement adds a step before contractors are paid, so ask about the timeline before you schedule rebuild work.
When a public adjuster makes sense
A licensed public adjuster works for you on the claim for a fee, which can help after a large or disputed loss. A restoration company cannot act as your adjuster while it does the repairs.
Hiring a Miami water damage company
Florida licenses the rebuild but not the water extraction and drying, so in Miami the screening comes from IICRC Certified Firm status, a written scope that names the water category and damage class, and proof of liability insurance. Ask for the firm's certificate number and confirm it with the IICRC, then check any rebuild license in the Florida DBPR license search before work starts.
 A written scope should name the water category and damage class, list the equipment counts, and promise daily moisture readings. Those are the same records an insurer asks for later.
In October 2024, Florida's Third District Court of Appeal, whose territory includes Miami-Dade County, ruled in Incident365 Florida v. Ocean Pointe V Condominium Association that disaster mitigation services such as water extraction, dehumidification, and antimicrobial application did not require a building contractor's license. The court sent the structural removal of damaged materials back to the trial court, and that task remains unsettled. Work that alters the building, along with plumbing, electrical, roofing, and air conditioning work, can still require the matching Florida license.
| Question to ask | A credible answer | A red flag |
|---|---|---|
| Are you an IICRC Certified Firm, and can I verify it? | A firm listing I can look up in the IICRC locator | A logo or a claim of certified technicians with no firm listing |
| What category and class is this water? | A written category and class, with the reason for each | No classification, or only the words water damage |
| Will I get a drying log? | Daily moisture readings and equipment counts | Equipment left running with no readings |
| Who holds the license for the rebuild? | A named Florida licensee whose license I can check | No license number, or a license for a different trade |
| Will you ask me to sign an assignment of benefits? | No, because Florida bans them on 2023 and later policies | Pressure to sign over your claim rights |
| How will you handle my deductible? | You pay it, and the company bills for the balance | An offer to waive or absorb it |
After a named storm, door to door solicitors and out of area crews appear within days. Ask for a local address and proof of liability insurance before anyone starts. Crews that follow storms may not know Miami-Dade permit offices and flood zone rules, which can stall a rebuild.
Ask each company for its equipment list, subcontractor names, and drying readings in writing, because a written scope lets you compare quality and not only price when choosing a water damage restoration company. Walk away from a company that will not put its drying plan on paper.
Water damage repair permits in Miami
Most cosmetic water damage repairs in Miami-Dade, such as painting and floor surfacing, do not need a building permit, but structural work always does, and plumbing, electrical, and mechanical repairs above the county's small dollar limits do too. Extraction and drying generally need no permit, so mitigation can begin the same day while permit questions are settled.
 Once a flood cut exposes wiring or supply lines, replacing them counts as new work and needs the matching trade permit. Get in writing who pulls each permit before the wall is closed.
Under Section 105.2 of the Florida Building Code, Miami-Dade County's permit exemptions list work that needs no permit, such as painting, floor surfacing, and stopping a leak in a drain pipe, and they cap licensed contractors' minor plumbing, mechanical, and nonstructural building repairs at $500 each, with roof covering repairs at $2,000. Each city enforces its own building department rules, so call the building department where the home sits before you start.
The City of Miami Beach's no-permit list shows how the line is drawn: stopping a leak in a drain or supply pipe is exempt, but replacing a concealed pipe counts as new work and needs a permit. Reconstruction that touches wiring, supply lines, or framing needs the matching trade permit.
A contractor should state in writing who pulls each permit, because the permit you need depends on the trade and on the home's flood zone. Unpermitted work can complicate a later insurance claim and a sale.
The 50 percent rule in Miami-Dade
In a flood zone, repairs that cost 50 percent or more of the structure's pre-damage market value count as substantial damage, and the building must then meet current floodplain requirements. FEMA says land value is not part of the calculation, and the local building official or floodplain manager makes the determination.
Meeting those requirements can mean elevating the home, and a permit is required for the repairs. The City of Miami Beach adds up permit values over the prior year and divides them by the Miami-Dade Property Appraiser's value, so earlier repairs count toward the 50 percent threshold.
NFIP policyholders in a special flood hazard area can receive up to $30,000 in Increased Cost of Compliance coverage toward those costs, and the claim is filed separately from the regular flood claim. Ask the city for a written substantial damage determination before you sign a reconstruction contract.
Federal help after a Miami flood
After a declared disaster, FEMA individual assistance helps with uninsured home repair needs, and SBA disaster loans of up to $500,000 can repair a primary residence. Neither replaces a claim with your own insurer, and both have deadlines that start at the declaration.
FEMA individual assistance requires a presidential major disaster declaration that covers Miami-Dade County, and registration typically closes about 60 days after it. Apply early and keep your insurer's decision letters on hand, because FEMA does not pay for losses insurance covers.
SBA disaster loans are not limited to businesses, and homeowners and renters can also borrow up to $100,000 to replace personal property. Terms can reach 30 years, which makes the loan a way to cover the gap between an insurance payment and the full cost of the work.
Condos and high rise units in Miami
In a Miami condo, the association insures the common elements and the owner's HO-6 policy covers the interior, so the first question after a leak is whether the water started inside the unit or in a shared system. Whether water damage in a condo is the association's cost or the owner's depends on where it started, and the declaration of condominium sets the boundary.
 Whether a leak like this is the association's cost or the owner's depends on where it started, and the declaration of condominium sets the boundary. Report it to building management in writing the same day.
Shared risers, drain lines, and air handler systems mean one failure can reach several units. Report a leak to building management in writing the same day, ask which shutoff to use, and request the master policy declarations page before you decide which claim to file.
Tenants report water damage to the landlord and insure their own belongings, and the landlord is generally responsible for the structure. Ask a restoration company whether it has worked in your building before, because crews unfamiliar with a tower's insurance and access approvals lose days.
Buying or selling a damaged Miami home
Florida Statute 689.302 requires a seller of residential property to give the buyer a flood disclosure at or before the time the contract is signed, and sellers must disclose whether they filed a flood claim or received flood related assistance. Changes effective October 1, 2025 also ask sellers to indicate known flooding that damaged the property during their ownership. Sellers must also disclose known material defects a buyer cannot readily see, such as active leaks, prior water damage, and recurring moisture.
Buyers should ask for repair invoices, the claim history, moisture readings, and any substantial damage determination for the property, because a clean permit record does not prove a dry history. Drywall, paint, and flooring repairs often need no permit, and fresh paint only on the lower walls can point to flood cuts and replacement.
Mold after water damage in Miami
A water loss in Miami becomes a mold job when drying lags, since mold can start growing on wet drywall and framing within 24–48 hours. Water damage restoration dries and repairs the structure, while mold remediation is a separate service under ANSI/IICRC S520.
A moisture reading that confirms materials are dry is the best protection against a later mold claim, so ask your restoration company for the readings in writing. Daily readings taken until the materials match an unaffected reference area also give an adjuster a dated record of when drying finished.
If mold appears after a loss, mold remediation in Miami is a separate project with its own licensing, written protocol, and clearance testing. Water dried inside two days rarely reaches that point.
Water damage risk across greater Miami
Water damage risk in greater Miami varies with elevation, distance from Biscayne Bay and the canals, and the age of the building more than with the ZIP code. Miami Beach and the barrier islands face tidal and surge flooding, while inland areas such as Hialeah and Doral flood mainly from heavy rain.
 Simplified map, not to scale. Confirm the flood zone for a specific address with the Miami-Dade Flood Zone Hotline at 305-372-6466, because insurers and permit offices use the map in effect.
Parcel level flood zones set insurance requirements, so look up the exact address and ask sellers about past flooding. Neighboring Broward County shares the same hurricane and tidal pattern but follows its own permit offices and floodplain administrators.
| Area | Main water risk | Where to start |
|---|---|---|
| Miami Beach and the barrier islands | King tides, storm surge, and street flooding in heavy rain; the city tracks repair costs over a year for the 50 percent rule | Check the flood zone and the cumulative repair rule before ordering repairs |
| Downtown and the Biscayne corridor | High rise units sharing risers and AC systems; Biscayne Boulevard near NE 15th Street flooded in November 2023 | Report in writing to building management and confirm the master policy |
| North Miami and Biscayne Park | The National Weather Service recorded 9.82 inches in North Miami and 10.12 inches in Biscayne Park over two days in November 2023 | Check the flood zone and first floor elevation before the next wet season |
| Coral Gables and South Miami | Older homes with original plumbing and tile roofs; Coral Gables took 9.37 inches of rain in the same November 2023 storm | Inspect supply lines, roof flashing, and the attic after storms |
| Homes on septic systems | Miami Waterkeeper counts about 120,000 septic tanks in the county, and rising water tables can saturate drain fields and push wastewater back into the house | Confirm whether the property is on sewer or septic, and have the drain field inspected after prolonged rain |
| Hialeah, Doral, and west Miami-Dade | Low elevation and slab construction; Miami Springs streets were impassable in November 2023, and apartment complexes flooded after Tropical Storm Isaac in 2012 | Inspect slab level plumbing, and check drainage and floodplain status |
How to prevent water damage in Miami
Four habits prevent most water damage in a Miami home: knowing the shutoff valves, replacing aging supply lines, shutting off the water when you travel, and carrying flood insurance. Most Miami losses start with a failed line, a storm opened roof, or a flood with no policy behind it, and these habits address all three.
 Braided stainless lines resist bursting better than rubber hoses and should be checked yearly. A floor sensor warns you of a slow hose or valve leak before it reaches the flooring.
Know your shutoff valves
Locate and test the main water shutoff and the valve at each appliance so you can stop a leak in seconds. Every hour a leak runs adds drying and replacement cost.
Shut off the water when you travel
Close the main valve before leaving for more than a few days, because a supply line failure in an empty home can run unnoticed for days. A leak detector that closes the main automatically adds a second layer for second homes and seasonal residences.
Replace hoses and supply lines before they fail
Braided stainless supply lines on washers, toilets, and sinks resist bursting better than rubber hoses and should be checked yearly. Replace rubber washing machine hoses about every five years.
Inspect the roof and attic after every named storm
Check flashing, ridge caps, tile, and the attic for wet insulation or stains after every named storm. A small opening repaired early costs far less than a collapsed ceiling.
Buy flood insurance before hurricane season
Hurricane season runs June 1 through November 30, so a flood policy has to be bought by early May to be active when it opens. Homeowners policies exclude flood damage entirely.
Frequently asked questions
How much does water damage restoration cost in Miami?
Typically $1,500–$7,000 for one affected area, based on RestoreAdvisor estimates. Contractors price water damage restoration cost per square foot at around $3–$7.50 for mitigation and $20–$37 for repairs, so an estimate far outside those ranges deserves an explanation line by line. Category 3 flood or tidal water on the ground floor can reach $10,000–$35,000 or more.
Does Florida homeowners insurance cover water damage from a pipe leak?
Usually yes, if the leak was sudden and accidental. A common exclusion removes coverage for damage from constant or repeated seepage or leakage over 14 or more days, so a slow leak can lose coverage for the later damage even when the first days are covered. A dated plumber invoice and photographs of the first stain show when the leak started.
Can I start drying before the insurance adjuster arrives?
Yes. Florida policies expect you to protect the property from further damage, so extraction and drying should start right away. Photograph the damage first, keep any removed material the adjuster may need to see, and keep receipts for equipment and labor.
Should I keep the air conditioning on while the home dries?
Usually yes, if the air handler and wiring stayed dry. Closed windows and running air conditioning pull moisture out of Miami's humid air, while an air handler that took on water should be inspected before it runs. Crews add dehumidifiers and air movers based on the structural drying plan for the loss.
Does flood insurance cover king tide flooding?
Often yes, when tidal overflow meets the NFIP flood definition. The NFIP defines a flood as a general and temporary condition of partial or complete inundation of two or more acres or two or more properties, and that includes overflow of tidal waters. Groundwater seepage and a drainage problem on a single property usually do not qualify, and any flood insurance policy still carries a 30 day waiting period.
How long does water damage restoration take in Miami?
Drying usually takes 3–7 days, and repairs add another 1–3 weeks. After a named storm, crew and material shortages can stretch both stages, and Category 3 flood jobs that need permits can run for months.
Can I stay in my Miami home during water damage restoration?
Often yes for a clean water leak confined to part of the home. Sewage, flood water, electrical hazards, or the loss of the only bathroom or air conditioning can make the home unsafe, and drying equipment adds noise and heat that matter in a Miami summer. Additional living expense coverage may pay for a hotel when a covered loss makes the home unlivable.
What if my restoration bill is more than my insurance pays?
You owe the difference. The contractor's agreement is with you, so the deductible, depreciation, and any uncovered work stay your responsibility, and Florida's ban on assignment of benefits means the company cannot collect from the insurer in your place on 2023 and later policies. Compare the insurer's estimate line by line and request a supplemental claim within 18 months if hidden damage turns up.
- IICRC S500
- IICRC S520
- EPA: Flood Cleanup to Protect Indoor Air and Your Health
- NWS Miami: Hurricane Andrew
- FEMA: Substantial Damage Determinations
- Florida Statutes: 627.70132 Notice of Property Insurance Claim
- Florida Statutes: 627.70131 Insurer's Duty to Acknowledge Communications Regarding Claims
- Florida Statutes: 627.7152 Assignment Agreements
- Florida Statutes: 689.302 Disclosure of Flood Risks to Prospective Purchaser
- Florida DFS: Florida's Hurricane Deductible
- Miami-Dade County: Permit Exemptions
- Citizens Property Insurance: Nonweather Water-Related Losses
- Florida DBPR: License Search
Sam Hickerson is the founder of RestoreAdvisor and writes consumer guides on mold remediation, water damage restoration, inspection, testing, and home recovery. His work focuses on helping homeowners understand costs, risks, and when to call a professional. He draws on guidance from the EPA, CDC, IICRC, and other authoritative sources to make complex home issues easier to navigate.